Buy Now Pay Later Flipkart: What Shoppers Should Know
Key Insights
Buy Now Pay Later (BNPL) allows customers to purchase products or services immediately and pay later in full or through smaller instalments, depending on the repayment plan.
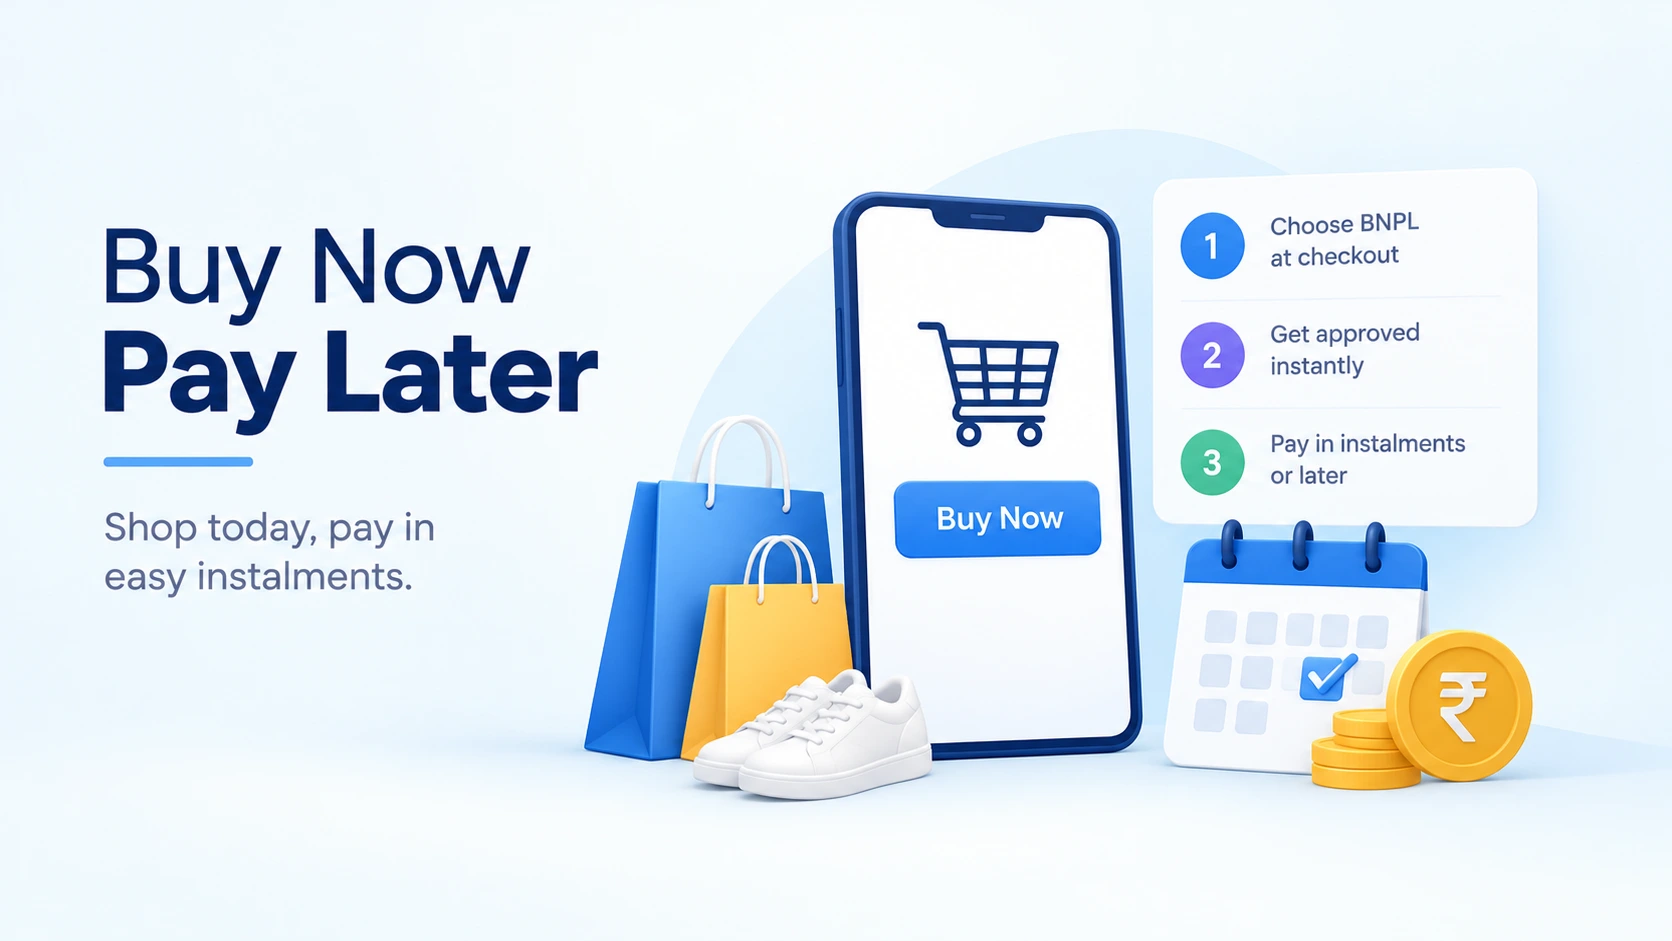
The BNPL process involves registering with a provider, receiving a credit limit, selecting BNPL at checkout, and repaying the amount by the due date.
Popular buy now pay later apps include Flipkart Pay Later, Amazon Pay Later, Simpl, LazyPay, and Paytm Postpaid. Their credit limits, repayment terms, fees, and merchant acceptance may vary.
BNPL offers benefits such as quick approval, better cash flow management, convenient payments, and potentially interest-free purchases. However, overspending, late fees, missed payments, and multiple outstanding dues can create financial challenges.
Responsible BNPL use involves borrowing only what you can repay, tracking upcoming payments, reading the terms carefully, avoiding multiple active plans, and choosing trusted, regulated providers.
In this blog, you'll learn what Buy Now Pay Later means, how it works, popular BNPL apps, Flipkart Pay Later, its benefits and risks, and practical tips for using BNPL responsibly.
Shopping habits have changed a great deal over the past few years. Instead of saving for months to buy a phone, a pair of shoes, or a set of kitchen appliances, many people now choose to pay in smaller parts over time. One of the most popular tools behind this shift is Buy Now Pay Later, often shortened to BNPL.
If you have seen options like "Pay in 3 installments" or "Pay next month" at checkout, you have already come across it. But what exactly is it, and is it a smart way to manage your money? In this blog, we explain Buy Now Pay Later in simple words, look at how it works, review popular apps, and share the benefits, risks, and tips you should know before using it.
Buy Now Pay Later is a short-term financing option that lets you purchase a product or service immediately and pay for it later. Instead of paying the full price at the time of purchase, you either delay the payment to a future date or split it into smaller installments.
Think of it as a mix between a credit card and an installment plan, but with a simpler process. In most cases, there is no long application form, no lengthy paperwork, and approval often comes within minutes. You are given a spending limit, and you can use it at partner stores, both online and offline.
BNPL generally comes in two common forms:
Pay later in full: You buy something today and pay the entire amount on a set date, such as the 15th of next month. Many apps offer this with no interest if you pay on time.
Pay in installments: The total amount is divided into equal parts, such as three or four payments over a few weeks or months. Some plans are interest-free, while longer plans may carry interest or fees.
The idea is not new. Layaway plans and store credit have existed for decades. What has changed is the technology. Today, Buy Now Pay Later is built into shopping apps and checkout pages, which makes it quick, convenient, and easy to access.
Many first-time users ask the same question: how does Buy Now Pay Later work behind the scenes? The process is straightforward and usually follows a few simple steps.
Step 1: Sign up or activate the service
You register with a BNPL provider or activate the feature inside a shopping app. You will typically be asked for basic details such as your name, phone number, PAN or other ID, and sometimes a selfie or bank account information for verification.
Step 2: Get a credit limit
The provider checks your eligibility. This may involve a soft look at your credit history, your income pattern, or your past behavior on the platform. Based on this, you receive a spending limit. New users often start with a small limit, which may increase as you repay on time.
Step 3: Choose BNPL at checkout
When you shop online or in a store that supports it, you select the Buy Now Pay Later option instead of a card, UPI, or net banking. The purchase amount is approved instantly against your limit, and the merchant receives the payment from the BNPL provider.
Step 4: Repay on the due date
You then repay the provider according to the plan you selected. This could be a single payment at the end of the billing cycle or several smaller installments. Most apps send reminders and let you pay through UPI, debit card, or netbanking. Some also offer auto-debit so you never miss a date.
Step 5: Build or lose trust
Paying on time usually keeps your account in good standing and can raise your limit. Paying late can lead to late fees, extra charges, a lower limit, or even a negative impact on your credit score, depending on the provider.
The key point is that Buy Now Pay Later is still borrowed money. The provider pays the seller on your behalf, and you owe that amount back. Understanding this clearly helps you use it responsibly.
Free Courses
Free FinTech Course – FinTech 101: Digital Banking & Payments
There is a wide range of buy now pay later apps available today, and each one works a little differently. Some are tied to a specific shopping platform, while others work across many merchants. Here are some of the well-known names, especially in India.
Flipkart Pay Later: Built into the Flipkart shopping app, it lets eligible customers shop now and pay later.
Amazon Pay Later: Available to eligible Amazon customers, it offers a credit line for purchases on the platform and some partner merchants, with options to pay later or in EMIs.
Simpl: A popular “pay in 3” style service that works across many online brands and delivery apps. Users typically get a monthly bill instead of paying at checkout.
LazyPay: A BNPL service offered by PayU Finance that works with many online merchants and allows short-term repayment cycles.
Paytm Postpaid: A service that gives users a monthly credit limit to use for bill payments, recharges, and shopping, with one consolidated bill at the end of the month.
Slice and other fintech apps: Several newer apps combine a spending limit with cards and installment options, often aimed at younger users and first-time borrowers.
When comparing buy now pay later apps, it helps to look at a few things: the credit limit offered, the repayment period, interest rates and fees, how many merchants accept the service, and how the provider reports your repayment behavior. Rules and offers change from time to time, so always read the latest terms inside the app before you start.
It is also worth noting that regulators in India, including theReserve Bank of India, have tightened rules around digital lending and credit products in recent years. Providers must follow guidelines on transparency, data handling, and who is allowed to extend credit. This is good news for customers, as it pushes the industry toward clearer practices.
Buy Now Pay Later Flipkart: What Shoppers Should Know
For millions of Indian shoppers, the first place they notice this payment style is on India’s largest e-commercemarketplaces. Buy now pay later Flipkart is offered through Flipkart Pay Later, a feature that lets eligible users buy products now and pay at a later date.
Here is a general idea of how it works on the platform:
Activation: You find the Pay Later option in your Flipkart app or at checkout and complete a quick verification using your mobile number and basic identity details.
Credit limit: Once approved, you get a limit that you can use for eligible purchases. The limit depends on factors such as your profile and shopping history.
Using it at checkout: When you place an order, you choose Flipkart Pay Later as your payment method. The amount is added to your Pay Later balance.
Repayment: You receive a bill that you pay by the due date, usually through UPI or another supported method. Some purchases may also be converted into EMIs, depending on the offer.
Shoppers like this option because it works well during big sale events. If you spot a deal on electronics or fashion but your salary has not arrived yet, you can still secure the offer and pay later. It also removes the need to carry a credit card.
That said, a few points deserve attention. Not every user is eligible, and the limit may be small at first. Not every product or category may be covered. Late payments can attract fees and may affect your future access. Terms, limits, and charges can change, so check the current details in the Flipkart app before relying on the feature for a large purchase.
Key Benefits of Buy Now Pay Later
There is a reason this payment method has grown so quickly. When used wisely, Buy Now Pay Later offers several real advantages.
Easy and quick approval
Traditional credit cards often require income proof, a credit history, and several days of processing. BNPL apps usually approve users in minutes, which makes them accessible to students, young professionals, and first-time borrowers.
Better cash flow management
Splitting a purchase into smaller parts reduces the immediate hit to your bank balance. This can help when you need to buy something important, such as a laptop for work or a refrigerator that suddenly stopped working, and you want to spread the cost.
Often interest-free
Many providers offer short-term plans without interest, as long as you pay on time. If you stay within the due date, you may pay exactly the same price as you would have paid upfront.
Simple and transparent process
With clear installment amounts and due dates, it can be easier to understand than some credit products with complex interest calculations. You know in advance how much you owe and when.
Helps build a credit record
Some providers report repayment behavior to credit bureaus. In such cases, timely payments can help you build a positive credit history, which may help when you apply for loans or credit cards later.
Convenience everywhere
Because BNPL is integrated into apps and online stores, you can use it in just a few taps. There is no need to enter long card details or wait for OTPs in many cases.
Risks and Drawbacks You Should Not Ignore
Like any financial product, Buy Now Pay Later has downsides. Being aware of them helps you avoid common mistakes.
Overspending: Since the money does not leave your account right away, it is easy to buy things you do not truly need. Small purchases can quietly add up.
Late fees and penalties: Missing a due date can lead to charges, and in some cases interest, which can make the purchase more expensive than expected.
Impact on credit score: If a provider reports missed payments, your credit score can suffer. This can make it harder to get loans later.
Multiple dues at once: Using several apps at the same time can make it difficult to keep track of what you owe and when.
Hidden terms: Some plans include processing fees, convenience charges, or higher interest on longer repayment periods. Always read the fine print.
Data privacy: Signing up requires sharing personal and financial details. Use only trusted, regulated providers.
The main lesson is simple: Buy Now Pay Later is a tool, and like any tool, its effect depends on how you use it.
Smart Tips for Using Buy Now Pay Later Responsibly
If you decide to use BNPL, these habits can help you stay in control.
Borrow only what you can repay. Before you buy, check that the installment or bill amount fits comfortably within your monthly budget.
Set reminders or auto-pay. A missed due date is the most common reason people face fees. Use calendar alerts or auto-debit to stay on track.
Avoid stacking multiple plans. Try to limit yourself to one or two active BNPL balances at a time, so your dues remain manageable.
Read the terms carefully. Look at interest rates, late fees, processing charges, and the exact due date before confirming a purchase.
Prioritize needs over wants. Use it for essential or planned purchases rather than impulse buys during sales.
Track your total dues. Keep a simple note or spreadsheet of all upcoming payments across apps.
Choose regulated providers. Stick to well-known apps and platforms that follow local lending rules and clearly explain their charges.
BNPL can suit people who have a steady income, a clear budget, and the discipline to repay on time. Students with part-time income, young professionals, and families who want to spread out the cost of a planned purchase often find it useful.
On the other hand, if you already struggle with existing debt, have an irregular income, or tend to overspend, it may be better to avoid it or use it very sparingly. Convenient credit is helpful only when you can repay it comfortably.
Final Thoughts
Buy Now Pay Later has made shopping more flexible by giving people the option to pay in smaller, more manageable parts. From dedicated buy now pay later apps to built-in features like Flipkart Pay Later, it has become a familiar part of everyday digital life.
Its biggest strengths are speed, simplicity, and, in many cases, zero interest when you pay on time. Its biggest risks are overspending and missed payments. If you understand how Buy Now Pay Later works, read the terms, and borrow only what you can afford, it can be a helpful and stress-free way to manage your purchases. Treat it as short-term support for your budget, not as extra income, and it will serve you well.
Frequently Asked Questions
No. Both let you spend now and pay later, but they work differently. A credit card gives you a revolving limit that you can use repeatedly, and unpaid balances usually carry interest. BNPL is generally a short-term arrangement tied to a specific purchase or billing cycle, with fixed repayment dates. Approval is also often faster and simpler with BNPL.
It can, depending on the provider. If the company reports your repayment history to credit bureaus, on-time payments may help your score, while late or missed payments can hurt it. Some providers do not report at all. Check the app’s policy so you know how your behavior is recorded.
The cost depends on the plan and the current terms. Many pay-later options do not charge interest if you repay by the due date, but late payments, EMI conversions, or special plans may include fees or interest. Always review the charges shown at checkout and in the Flipkart app before you confirm an order.
Most reputable apps are safe when they follow regulatory guidelines and use secure systems to protect your data. To stay safe, download apps only from official stores, avoid sharing OTPs or passwords, read the privacy policy, and choose providers that clearly explain their fees and repayment rules.
Arif Siddiqui
Head of Accounting and Treasury
Arif Siddiqui is a finance leader specializing in accounting, treasury, and financial strategy. As Head of Finance at Generali Employee Benefits, he brings extensive experience in managing global financial operations. He is known for driving financial efficiency and governance across organizations. His leadership supports sustainable business growth and financial excellence.
Get Free Upskilling Guidance
Fill in the details for a free consultation
Related Courses
Explore our programs
Post Graduate Certificate Programme in FinTech, AI in Finance, and Risk Management

 October 30, 2026
 10 min read



 Key Insights
 ChatGPT
 Perplexity
 Claude
 Grok





 ROI Calculator